Bank Zenit
 Renaissance Bank
 LOCO-Bank
 T-Bank
 Bank Sinara
 Credit Europe Bank






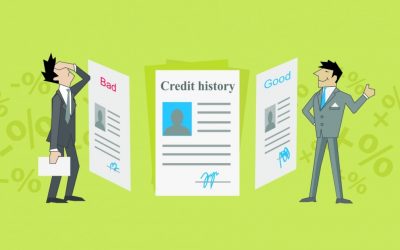
Do microloans affect credit history?

What is a credit history?
A credit history is your dossier as a borrower. By looking at it, a potential lender can draw conclusions about how responsibly you handle debt repayments, whether you have had issues paying off other loans, what your debt load is at the time of applying to the bank, and so on.
What information does a credit history contain?
There are no uniform rules for formatting a credit history—its appearance may vary depending on the credit history bureau. Nevertheless, it consists of four mandatory parts: title, main, informational, and closed. Let's discuss each of them in more detail:
- Title section. This section contains all information about the credit history subject — their full name, passport data, tax ID (INN), insurance number (SNILS), date and place of birth, and so on.
- Main section. In this section, a potential lender can see what loans you have at the time of application, whether funds are being recovered from you to cover debt, and whether you have initiated bankruptcy proceedings.
- Informational section. It contains information about all applications submitted to credit organizations and the results of their review.
- Closed section. It is only accessible to the subject of the credit history themselves. In this section, they can see which credit organizations have requested their dossier.
What kind of credit history is considered good?
Credit organizations evaluate credit histories differently — some lenders turn a blind eye to long-term defaults on loan obligations, while others are picky about even minor payment delays.
Overall, however, the following credit history is considered good:
- Without payment delays. It is desirable that you have no loan debts at all. But, as we mentioned, some lenders overlook minor delays.
- Without mass loan applications. A large number of inquiries to credit organizations can signal to a lender that you have financial problems and may not be able to repay the loan issued to you.
- Without a high debt load. The more active loans you have at the time of application, the higher the probability that your request will be denied. You risk being unable to cope with a large number of obligations and missing payments.
- With previously repaid loans. A blank credit history does not characterize you as a borrower — the bank cannot conclude how responsibly you treat your obligations. The more paid-off loans you have, the more favorable you look in the eyes of a potential lender.
Do microfinance organizations transmit information to credit history bureaus (CHBs)?
MFIs are the exact same credit organizations as banks. They operate legally and therefore must comply with all current legislation norms. This means microfinance companies are required in any case to transfer information about borrowers and potential clients to Credit History Bureaus.
You can check whether the company you plan to apply to operates legally on the website of the Central Bank of the Russian Federation. All registered microfinance organizations are included in the registry of MFIs of the Russian Federation.
Подберем предложения под вашу ситуацию
Оставьте телефон — покажем варианты с высокой вероятностью одобрения и актуальными условиями.
- Проверенные предложения
- Без звонков от менеджеров
- Результат в удобном канале
How do microloans affect credit history?
Let's move on to the article's topic and discuss whether microloans affect your credit history. Any lender you apply to is required to transfer information about you to a Credit History Bureau. There are currently seven of them in Russia:
- JSC "National Bureau of Credit Histories";
- JSC "United Credit Bureau";
- LLC "Russian Standard Credit Bureau";
- LLC "Equifax Credit History Bureau";
- LLC "East-European Bureau";
- LLC "Capital Credit Bureau";
- LLC "Interregional Credit History Bureau".
Credit organizations can cooperate with any credit history bureaus. Therefore, information about you may be contained in one or several bureaus.
Microloans can both improve and worsen your credit history. For instance, if you take out a long-term loan to buy a car and pay it off according to the schedule, a future lender will see this as a sign that you treat your obligations responsibly and can be trusted.
The exact opposite happens if you regularly take out microloans for small amounts. For a lending institution, this is a signal that you have ongoing financial difficulties and may become a high-risk customer.
Answering frequent questions
Finally, we will answer the most frequently asked questions on the topic of the article.
Can I fix my credit history using MFIs?
Some microfinance organizations do offer credit history improvement services. Do they work? More likely no than yes. After completing such programs, you will probably be able to get loans. But only from the same microfinance organizations. Banks will most likely continue to deny you loans with a high probability.
What will happen if I apply to several MFIs at once and they turn me down?
In any case, this information will be reflected in your credit history. In the future, this may negatively affect your cooperation with banks.
Can I start taking out microloans if I have a zero credit history?
If you want to take out a microloan solely to build a credit history, it is better to abandon the idea. In this case, you are better off applying for a small commodity loan.
I took out a microloan from an individual. Will this information be reflected in my credit history?
If your lender operates illegally, your loan information will likely not be in your credit history. However, all legal MFIs are required to transfer data to Credit History Bureaus.
I missed a payment on my microloan. How quickly will this information appear in my credit history?
Banks and microfinance organizations submit information to CHBs no later than the end of the second business day following the day the information was received.
An MFI claims in its advertising that it does not transfer data to CHBs. Is this true?
Most likely, a microfinance organization making such a promise in its advertising is intentionally misleading consumers. After all, any lending company registered in the register of the Central Bank of the Russian Federation is required to transfer data to Credit History Bureaus.
If an MFI really does not transfer borrower data to CHBs, it is safe to say that the company is operating illegally. We, in turn, do not recommend contacting such lenders.
What information do microfinance organizations transfer to CHBs?
MFIs transfer the exact same data to Credit History Bureaus as banks do:
- information about a client's application to a microfinance organization, even if their application was rejected;
- information about the borrower receiving a microloan;
- the procedure for fulfilling obligations to the organization;
- information on the full repayment of the debt;
- data on overdue payments;
- data on transferring a case to court if the microfinance organization has decided to recover the debt from the borrower.
To sum up. It is practically impossible to improve your credit history through microloans — banks look negatively on borrowers who take loans from MFIs. An exception may be a long-term loan for a term of six months to a year.
Loan term up to 30 days
From %
Amount - up to 30,000 RUB
CREDIT HISTORY —
Loan term up to 365 days
From %
Amount — up to 100,000 RUB
CREDIT HISTORY —
Loan term up to 365 days
From %
Amount — up to 150,000 RUB
CREDIT HISTORY —
Other posts