Bank Zenit
 Renaissance Bank
 LOCO-Bank
 T-Bank
 Bank Sinara
 Credit Europe Bank






Debt collection under a writ of execution

The concept of a writ of execution and its features
Upon reviewing the statement of claim and issuing a ruling, the court is required to provide a writ of execution — an official document on the basis of which bailiffs will subsequently act. The contents of the writ of execution are regulated by Article 13 of Federal Law No. 229-FZ.
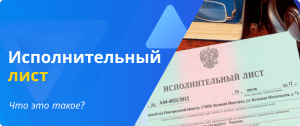
The writ of execution must contain the following information:
- The address and name of the court that considered the case based on the statement of claim, as well as the last name and initials of the official, i.e., the judge who issued the writ of execution.
- The name and case number.
- The date the judicial act was adopted.
- The date the judicial act entered into legal force.
- Information about the claimant and the debtor.
- The date of issuance of the writ of execution.
In addition to the information indicated above, the writ of execution must contain the judge's signature and the official seal of the court. To prevent document forgery, the writ of execution is printed on special paper with security elements, such as watermarks and consecutive numbering.
Procedure for debt recovery under a writ of execution
After a court ruling is issued, the plaintiff has two ways to recover the debt: independently or through bailiffs. If you decide to act on your own, you will need to find out which bank the debtor keeps their money in and where they are employed. You can do this through the Federal Tax Service. To do this, you will need to present them with a valid writ of execution. So, you have found out which bank serves the defendant and who their employer is. Your next steps will be as follows:
- You must send the writ of execution to the financial institution where the debtor's money is kept. Upon receiving the writ, the bank will freeze all available funds regardless of the defendant's wishes. If there are several such banks, you will need to obtain copies of the writ of execution, notarize them, and send them to each organization.
- The second option is to send the writ of execution to the employer's address. In this case, you will monthly receive no more than 70% of the debtor's salary until the debt is fully paid off.
The second method is recovery through bailiffs, which is much simpler since all the actions outlined above will fall on the shoulders of the Federal Bailiff Service. Along with the writ of execution, you must submit an application requesting case review.
Bailiffs are endowed with greater powers than ordinary citizens, so getting money through them is much easier and faster. Thus, the Federal Bailiff Service can:
- freeze the defendant's bank accounts;
- inventory and sell the debtor's property to pay off the debt;
- impose a ban on leaving the country;
- revoke driver's licenses;
- withhold a portion of the defendant's salary.
Подберем предложения под вашу ситуацию
Оставьте телефон — покажем варианты с высокой вероятностью одобрения и актуальными условиями.
- Проверенные предложения
- Без звонков от менеджеров
- Результат в удобном канале
How debt recovery under a writ of execution takes place
The collection procedure will vary somewhat depending on the debtor's capabilities and their willingness to repay the debt. However, debt collection most commonly includes the following stages:
- initiation of enforcement proceedings;
- offering the debtor the opportunity to voluntarily pay off the debt to the creditor;
- sending requests to government agencies to locate the debtor's property;
- sending the writ of execution to the bank and the workplace;
- imposing restrictions on travel outside the country;
- assessing the value of the property and transferring it for sale;
- transferring the proceeds to the creditor;
- collection of the enforcement fee;
- termination of enforcement proceedings.
Timeframe for debt recovery under a writ of execution
First, there is a limitation period. It is three years, which means that the creditor has 36 months to submit the writ of execution to the bailiffs. However, there are nuances here:
- The plaintiff may not rush to contact the bailiffs if the court has ordered recovery in regular payments. The clearest example of such a situation is alimony payments. In this case, the limitation period begins to be calculated not from the moment the court makes a decision, but from the moment of the last expected payment, that is, after the child reaches adulthood.
- The reverse situation arises when the plaintiff went to court to return a minor child taken from the defendant. In this case, it is necessary to contact the bailiffs no later than a year after the decision is made.
The limitation period may be interrupted. This happens in two cases:
- when the plaintiff contacts the bailiffs to open enforcement proceedings;
- when the defendant partially repays the debt.
In these cases, the calculation of the limitation period starts anew, even if only a few weeks were left before its expiration.
In turn, the writ of execution held by the bailiffs will remain valid either until the debt is fully closed, or for two months if it is impossible to collect the debt due to the debtor's lack of property.
Note.
If debt collection is impossible, the bailiff is forced to return the writ of execution to the plaintiff. However, the creditor can resume enforcement proceedings six months after receiving the writ of execution.
In some cases, the plaintiff can restore the limitation period if it was missed for a valid reason:
- due to an illness involving prolonged hospitalization;
- temporary absence, for example, a business trip;
- lack of knowledge about the court decision.
When bailiffs cannot write off a debt
The only situation when a bailiff cannot write off a debt under a writ of execution is individual bankruptcy. That is, if the defendant applies to the Arbitration Court with an application to declare themselves bankrupt and the judge satisfies their claim, the bailiff will not be able to collect the existing debt from them.
However, this is not relevant for all types of debts. Thus, bankruptcy will not help avoid the collection of:
- alimony;
- compensation to third parties for causing damage to their property, health, or life;
- subsidiary liability;
- debts to former employees of individual entrepreneurs.
How to suspend a writ of execution
All parties to the process can suspend the debt collection procedure:
- the bailiff;
- the judge;
- the plaintiff;
- the defendant.
Most often, debtors apply for the suspension of the writ of execution because they believe that in this way they can avoid responsibility altogether.
In order to suspend the writ of execution, the defendant must apply to the court or the Federal Bailiff Service with an application containing a truly valid reason. Legal grounds on which a debtor can receive a deferral include:
- the defendant's disagreement with the appraised value of their property;
- disagreement with the sale of specific property items toward the debt;
- disagreement with the amount of the enforcement fee.
In addition, the reasons for suspending a writ of execution may include:
- declaration of the debtor as deceased or missing;
- loss of legal capacity;
- participation of the debtor in military operations;
- revocation of the creditor's license;
- initiation of bankruptcy proceedings;
- absence of property that can be levied upon.
For the same reasons, other parties to the proceedings may also suspend enforcement proceedings.
Loan term up to 365 days
From %
Amount — up to 100,000 RUB
CREDIT HISTORY —
Loan term up to 30 days
From %
Amount - up to 30,000 RUB
CREDIT HISTORY —
Fee-free withdrawal up to RUB
Up to %
Cashback type —
Cashback —
Other posts